Risky VAT payer status: how businesses should act
Contents
A decision determining that a VAT payer meets the risk criteria does not assess any tax liabilities or impose penalties. At the same time, such a decision may have significant adverse consequences for a business, including the suspension of VAT invoice registration, complications for counterparties in claiming input VAT, and, as a result, the risk of disruption or termination of business relationships.
In this article, we outline a practical course of action after receiving a decision classifying a taxpayer as risky and highlight the key aspects to consider to protect the taxpayer’s interests.
Identifying the grounds for the risk status decision
The first step upon receipt of a decision determining that a taxpayer meets the risk criteria should be to identify the specific grounds for the decision.
The decision must specify the grounds and information based on which the taxpayer was classified as risky. In practice, however, such decisions often contain only a general reference to the relevant risk criterion without properly identifying the underlying facts and circumstances.
This is particularly common where criterion 8 of the risk criteria is applied, and the tax authority refers to information regarding the risky nature of a business transaction carried out by the taxpayer. In such a case, it is important to understand which specific transactions, counterparties, and periods served as the basis for the tax authority’s conclusions.
If this is unclear from the content of the decision, it is advisable to obtain additional information from the tax authority, in particular by submitting an attorney’s request or a request for public information.
Understanding the specific grounds on which the taxpayer was classified as risky makes it possible to determine which documents and explanations to prepare to rebut the risk status and to develop an effective defense strategy.
Submission of explanations and supporting documents to the tax authority
The next possible step, after receiving and analyzing the decision that the taxpayer meets the risk criteria, is to submit explanations (information and supporting documents) to the regional-level commission of the tax authority to rebut the identified risk indicators and secure the taxpayer’s removal from the list of risky VAT payers.
Such explanations should not be merely formal in nature. Their content should directly address and rebut the specific circumstances that served as the basis for the risk status decision.
The legislation provides only an indicative list of documents that may be submitted to demonstrate that the taxpayer does not meet the risk criteria. The final scope of supporting documentation will depend on the specific nature of the taxpayer’s business activities and the grounds on which it was included in the list of risky taxpayers.
It should also be considered that a VAT payer may submit explanations and documents seeking removal from the list of risky taxpayers an unlimited number of times, provided that the taxpayer has not used the administrative appeal procedure.
In practice, taxpayers often ask whether they must submit such explanations before applying to court, or whether they may challenge the risk status decision immediately.
From a practical perspective, submitting explanations and supporting documents is advisable for two principal reasons.
First, even at this stage, the taxpayer may receive a favorable decision and be removed from the list of risky taxpayers without the need for judicial appeal.
In addition, properly prepared explanations and supporting documents help establish an evidentiary record that may subsequently be relied upon in administrative or judicial appeal proceedings.
Second, court practice concerning whether explanations and supporting documents must be submitted before bringing a court claim remains relatively inconsistent.
For example, in its resolution dated November 18, 2025, in case No. 140/6764/24, the Supreme Court stated that submission of explanations and supporting documents to the regional-level commission of the tax authority is not a mandatory prerequisite for bringing a court claim.
At the same time, recent lower-court case law reflects the opposite approach when assessing whether a taxpayer must first provide explanations and documents to the tax authority.
For example, in its resolution dated February 19, 2026, in case No. 160/12255/25, the Third Administrative Court of Appeal stated: “the court may not assume the functions of the controlling authority, and specifically those of the regional-level commission responsible for the suspension of registration of VAT invoices/adjustment calculations in the VAT Invoice Register, by assessing documents and information submitted by the claimant exclusively to the court for the purpose of rebutting the risk indicators identified by the commission and specified in the contested decision, as doing so would be inconsistent with the purpose of administrative justice”.
The Eighth Administrative Court of Appeal reached a similar conclusion regarding the need to submit explanations and documents to the regional-level commission before bringing a court claim in its resolution dated March 30, 2026, in case No. 140/8632/24.
In light of the above, submitting explanations and supporting documents is an advisable stage of the defense strategy that should not be overlooked.
Administrative appeal procedure
Even if a taxpayer submits well-prepared explanations and supporting documents demonstrating that it does not meet the risk criteria, the regional-level commission may reject those arguments and leave the taxpayer on the list of risky taxpayers.
In such circumstances, the next possible step for the VAT payer may be to initiate the administrative appeal procedure by filing an appeal against the regional-level commission’s decision with the central-level commission of the State Tax Service of Ukraine.
The administrative appeal procedure offers certain practical advantages. Unlike the procedure for submitting explanations, the taxpayer may participate in the consideration of its appeal and further substantiate its position directly before the tax authority.
In addition, as part of these proceedings, the taxpayer may involve representatives of specialised business organisations, such as the Business Ombudsman Council, or other institutions that protect business interests.
In practice, using these additional mechanisms can strengthen the taxpayer’s arguments and draw additional attention to the lack of proper grounds for the risk status decision.
Judicial appeal
The final step to protect the taxpayer’s rights is to challenge the decision before a court.
A VAT payer may initiate court proceedings either after completing the administrative appeal procedure or directly after receiving a negative decision from the regional-level commission, preferably after the commission has considered the explanations and supporting documents the taxpayer previously submitted.
In judicial proceedings, the taxpayer’s position should generally be structured around two key lines of argument:
- demonstrating that there were no substantive grounds for classifying the VAT payer as risky.
In this context, the statement of claim should consider the explanations and documents previously submitted to the tax authority (if any). This ensures the consistency of the taxpayer’s legal position, allows demonstrating good faith when interacting with the tax authority, and strengthens the second line of argument described below;
- demonstrating procedural violations committed by the tax authority when adopting the risk status decision (such as the failure to assess the taxpayer’s documents and explanations properly or to explain why the submitted documents did not rebut the tax authority’s conclusions).
For example, in its resolution dated July 2, 2026, in case No. 440/10955/24, the Supreme Court took into account that the tax authority had failed to specify which documents the taxpayer was required to submit, had not identified the period for which such documents were required and had not explained why the documents previously submitted by the taxpayer did not rebut the grounds underlying its risk status.
The Supreme Court concluded that this conduct did not comply with the law’s requirements, as it deprived the taxpayer of the ability to understand which specific circumstances it had to rebut and which documents it had to submit in support of its position.
Thus, when challenging a risk status decision before a court, it is advisable to rebut both the tax authority’s substantive conclusions and, where applicable, to draw the court’s attention to deficiencies in the decision-making procedure and in the reasoning provided by the tax authority.
To summarize, Ukrainian legislation provides certain mechanisms a VAT payer may use after receiving a decision determining that it meets the risk criteria: submitting explanations and supporting documents (which may be done repeatedly) and filing administrative and judicial appeals.
At the same time, the effectiveness of protection largely depends on a well-chosen strategy and the quality of the evidentiary base.
A properly structured approach enables the company to rebut the tax authority’s conclusions, secure its removal from the list of risky VAT payers and restore its normal business operations as soon as possible.
GOLAW provides comprehensive legal support to VAT payers seeking removal from the list of risky taxpayers – from the initial assessment of the situation and development of the optimal strategy to administrative and judicial appeals. We support our clients at every stage, ensuring proper preparation and effective implementation of the selected defense strategy.
The article was written by:
Viktoriia Bublichenko, Partner at GOLAW, Head of Tax, Restructuring, Claims and Recoveries practice, Attorney at law
Tetiana Fedorenko, Senior Associate at Tax, Restructuring, Claims and Recoveries practice at GOLAW, Attorney at law
Anna Kostsova, Junior Associate at Tax, Restructuring, Claims and Recoveries practice at GOLAW
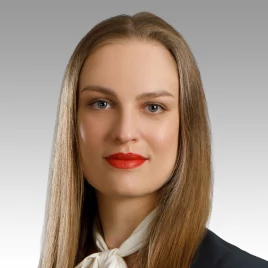
Viktoriia Bublichenko
Partner, Head of Tax, Restructuring, Claims and Recoveries practice, Attorney at law
- Contacts
- 31/33 Kniaziv Ostrozkykh St, Zorianyi Business Center, Kyiv, Ukraine, 01010
- v.bublichenko@golaw.ua
- +38 044 581 1220
- Recognitions
- ITR World Tax 2026
- Lexology Index: Corporate Tax 2025
- IFLR 1000 2024
- 50 Leading Law Firms Ukraine 2026
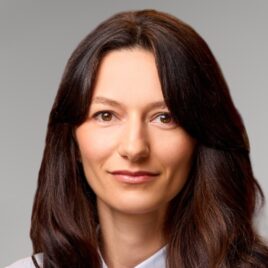
Tetiana Fedorenko
Senior Associate, Attorney at law
- Contacts
- 31/33 Kniaziv Ostrozkykh St, Zorianyi Business Center, Kyiv, Ukraine, 01010
- t.fedorenko@golaw.ua
- +380 44 581 1220
- Recognitions
- ITR World Tax 2026
Get in touch
To get a consultation, please fill out the form below or call us right away:
 We respond within 2 hours on business days
31/33 Kniaziv Ostrozkykh st, Kyiv
 All data is protected by attorney-client privilege in accordance with Article 22 of the Law of Ukraine “On the Bar and the Practice of Law.”
Sign up to be aware
New achievements are inspired by information. GO further, don’t miss out GOLAW news and legal alerts
We use cookies to improve performance of our website and your user experience.
Cookies policy
Cookies settings


